
Buying an Existing Business? What Seller Financing Actually Means for You
TL;DR
Seller financing lets you buy a business by paying the previous owner over time instead of all at once, but it only works if you do real due diligence, get every term in writing, and plan the handoff on purpose.
What Seller Financing Actually Is
Seller financing means the person selling the business acts like the bank. Instead of you paying the full purchase price at closing, you pay a down payment up front and sign a promissory note for the rest, then pay the seller back in installments, with interest, over an agreed number of years. The seller keeps a legal interest in the business until the note is paid off, which is their protection if things go sideways. It is different from a lease-to-own arrangement, where you are renting with an option to buy, and different from an earn-out, where the final price depends on how the business performs after you take over. With seller financing, the price is set at closing. What changes is when you pay it.
Sellers offer this because it gets the business sold faster and gives them a stream of income instead of one lump sum, which can also spread out their tax bill on the sale rather than taking the full gain in one year. Buyers accept it because banks are often reluctant to lend against a small, owner-operated business the way they will against a building or a piece of equipment. A restaurant's real value is its regulars, its recipes, and its relationship with a landlord and suppliers, none of which shows up as collateral a bank can repossess. Seller financing bridges that gap: the person who actually knows the business is the one extending the credit.
Why This Comes Up So Often With Hmong-Owned Businesses
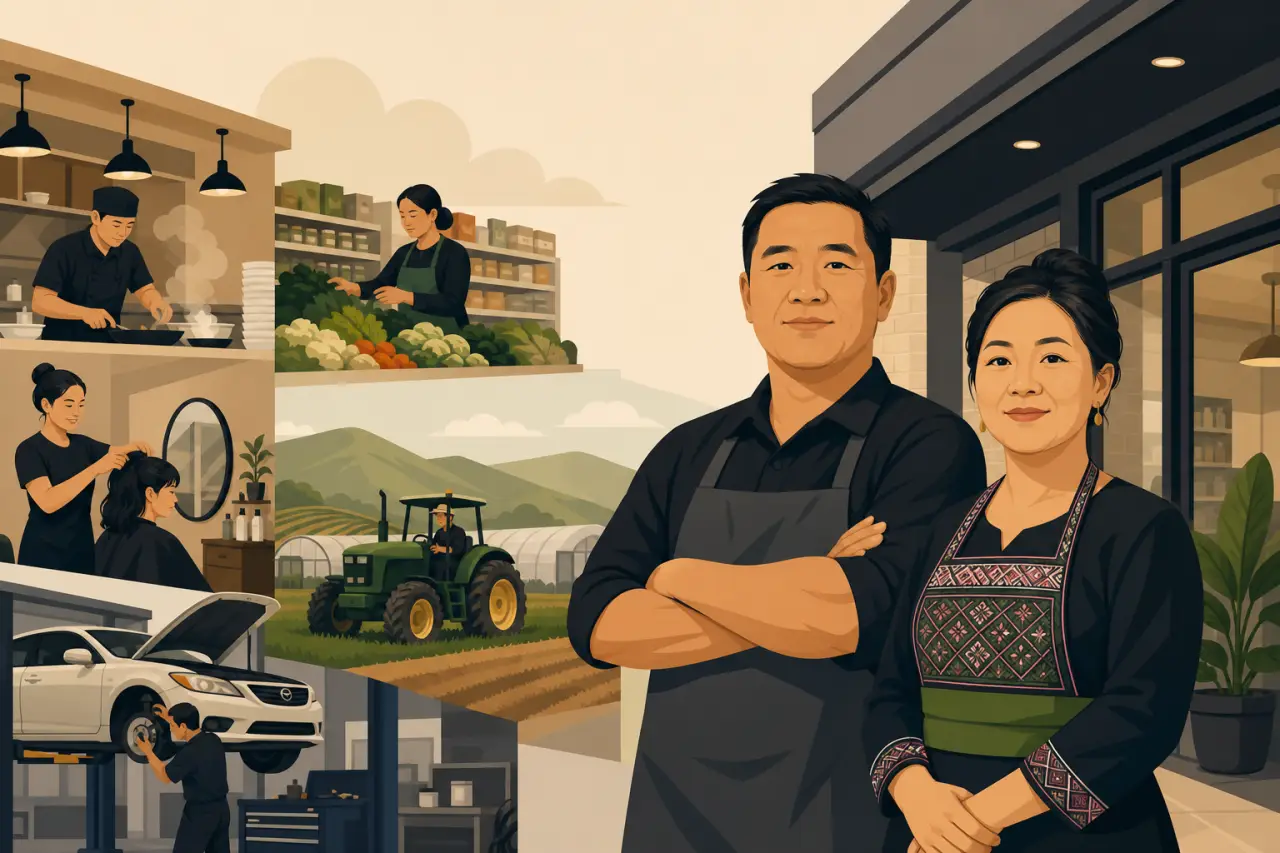
A lot of Hmong-owned businesses are cash businesses run with family labor, and the books often do not look the way a bank underwriter wants them to. Common examples include:
- Restaurants
- Grocery and specialty markets
- Salons
- Farms
- Auto shops
Some family members work without being on formal payroll, tips and cash sales are not always fully reflected in reported revenue, and there may be no dedicated bookkeeper cleaning up the financials for a loan application. None of that means the business is not real or not valuable. It means a conventional bank loan is often a hard fit, and a seller who already trusts the buyer is frequently the only realistic source of financing.
These sales are also often generational or community-based: a parent selling to a son or daughter, an owner selling to a longtime employee, or a sale between two families who already know each other through church, clan associations, or years of doing business together. That existing trust is a real asset, it is often why the deal is possible at all, but it can also be exactly why people skip the paperwork. Treating a relative or a respected elder's word as a substitute for a written contract is understandable and also the single most common way these deals go wrong. If anything, put more care into the paperwork when the relationship matters to you, not less, because an unwound handshake deal damages the relationship far worse than a contract negotiation ever would.
How the Deal Actually Gets Structured
Most seller-financed small business sales share a similar shape. The buyer puts down somewhere between ten and thirty percent of the purchase price in cash at closing, sometimes more if the seller wants a bigger cushion. The remaining balance becomes a promissory note with a stated interest rate, usually somewhere close to what a bank would charge, and a repayment term, commonly three to seven years. Some notes are structured with a balloon payment at the end, meaning the monthly payments are calculated on a longer schedule but the full remaining balance comes due earlier, which buyers sometimes plan to refinance through a bank once the business has a track record under new ownership.
Beyond the basic payment terms, a few other provisions typically show up in how the deal is structured:
- The seller almost always takes a security interest in the business assets, inventory, equipment, sometimes the business name and customer list, filed as a UCC-1 lien, so if you default they have a legal claim to reclaim those assets rather than just an unenforceable promise.
- Many sellers also require a personal guarantee, which means you are personally on the hook for the note even if the business itself cannot pay, not just the business entity. That is exactly why choosing the right business structure before you sign is worth doing early, since how you hold the business affects how cleanly that guarantee can eventually be separated from your other personal assets.
- If you are also trying to bring in an SBA loan to cover part of the price or fund renovations, the seller's note usually has to be subordinated, meaning the bank gets paid first if things go wrong.
- It is common, and worth asking for, to hold back a portion of the purchase price in escrow for several months after closing specifically to cover any liability that turns up that the seller did not disclose.
The Due Diligence You Cannot Skip
Ask for at least three years of actual tax returns, not just a profit and loss statement the seller put together themselves, since a P&L can be shaped to look however someone wants it to look and a tax return is what they told the IRS. Where you can, reconcile reported revenue against bank deposits over a similar period, and pay attention to seasonality, a Hmong New Year market vendor or a restaurant near a fairgrounds may have months that carry the whole year, and you need to know that pattern before you agree to a flat monthly note payment.
Beyond the numbers, work through the following before you sign anything:
- Check for existing debts and liens against the business itself, a UCC search will show if there is already a lender with a claim on the same equipment being sold to you.
- Ask specifically about unpaid sales tax, in many states unpaid sales tax follows the business to its new owner as successor liability, meaning you could inherit a bill you never created.
- If the business operates out of a leased space, get the actual lease and confirm it can be assigned to you and how much term is left, a business with two years left on its lease is worth less than one with ten.
- Confirm every license and permit transfers cleanly, a liquor license, a health department permit, a cosmetology license, since some of these do not automatically transfer with a change of ownership and require their own application.
- Walk the kitchen, the salon stations, the walk-in cooler, whatever the physical backbone of the business is, and get a real sense of what needs replacing soon.
- Ask the seller directly, more than once and in more than one way, why they are actually selling. Retirement and a family move are common and fine. A vague answer to a direct question is not.
Get Every Term in Writing, Reviewed by Someone Who Works for You
The promissory note itself needs to spell out:
- The principal amount
- The interest rate
- The exact payment schedule and due dates
- The maturity date
- What counts as late
- What happens if you miss a payment, including how many days you have to cure it before the seller can call the whole balance due or move to repossess assets
Vague language here is where good relationships turn into disputes later.
Beyond the note, negotiate a non-compete clause that keeps the seller from opening a similar business down the street and pulling your customers with them, with a specific radius and time period written in, not just a general promise. Negotiate a transition or consulting period with actual hours and a duration, thirty to ninety days is common, so the seller's help after closing is a contractual obligation and not something that depends on their mood. Ask for the right to review the business's books during the entire period you are still making payments, since you are financially exposed to how the business performs long after closing day. And use an attorney and an accountant who work for you, not the seller's advisors doing you a favor, even if that costs real money up front, ideally someone who has actually handled small business acquisitions before and, if language is a barrier for anyone involved, someone who can walk through every clause in a language everyone in the deal actually understands.
Plan the Handoff So Customers and Staff Actually Stick Around
The businesses that survive an ownership change are usually the ones where the transition was planned, not improvised, the same discipline behind building a business that lasts long after the sale itself is final. Negotiate the seller's post-closing involvement into the contract itself, a period where they are physically present, introducing you to suppliers and regular customers, showing you how orders actually get placed and how the walk-in cooler actually gets managed, not just what is written in a manual. Have that presence taper off on a schedule you both agree to, rather than the seller either disappearing the day after closing or never quite letting go.
Tell key employees what is happening as early as you reasonably can, not the morning of closing, since losing your best cook or your most trusted stylist right before or after a sale can do more damage than almost anything else in the deal. Loyal customers who have known the previous owner for years are watching closely for signs that something has changed, a personal introduction from the seller, keeping the hours and the menu or service list stable for the first several months, and a visible, friendly handoff will do far more to keep them than any announcement or advertisement. Save the rebrand, the new sign, the new hours, for after you have had a real season to build trust in your own right.
What Can Go Wrong, and How to Protect Yourself
Sometimes a seller who agreed to step back keeps showing up and second-guessing your decisions in front of staff or customers, which undermines you before you have had a chance to establish yourself. Sometimes a liability the due diligence missed surfaces anyway, a supplier who was never paid, a customer complaint that was quietly settled and never disclosed. And sometimes the business simply performs worse under new ownership for reasons that have nothing to do with you, a competitor opens nearby, a key employee leaves, the local economy softens, and the note payment that looked manageable on paper becomes a real strain.
There are concrete ways to protect yourself at each stage:
- Protect yourself on the front end by holding back part of the purchase price in escrow for a defined window after closing, and by getting real representations and warranties written into the purchase agreement, meaning the seller is legally on the hook if they misstated something material about the business.
- Protect yourself during the note period by building in a workout provision, a defined process for renegotiating payments if the business hits a rough patch, rather than a contract that jumps straight from a missed payment to full default and repossession.
- Go in with clear eyes about the personal guarantee: if you sign one, a business downturn is not just a business problem, it is a personal financial exposure, and you should know exactly what that means for your house, your savings, and your family before you sign it, not after.
Deciding Whether the Deal Is Actually Worth It
Before you commit, run the business's real cash flow, not the seller's pitch, against your total obligation:
- The note payment
- Any lease payment
- Payroll
- Supplies
- A livable wage for yourself
Get clear on paying yourself after the purchase before you sign anything, since undercutting your own pay just to make the note easier only trades one financial strain for another. If the numbers only work in a best-case month, they will not survive a slow one. It is also worth checking whether seller financing has to be the only source of capital, some deals combine a smaller SBA loan with the seller carrying a second, subordinated note, which can lower your monthly obligation to the seller while still avoiding the full weight of a conventional loan.
Know your walk-away signals going in: a seller who will not produce real tax returns, who resists putting the deal in writing, or who cannot give you a straight answer about why they are selling is telling you something, even if the relationship makes it uncomfortable to hear. When the numbers hold up and the paperwork is real, seller financing is one of the most workable ways to buy into business ownership without already having institutional wealth or a long credit history, and it can still be the right move even if you are also rebuilding your credit first rather than starting from a clean financial slate, and it is a major reason ownership of Hmong-owned businesses is able to pass within families and communities instead of being sold off to whoever has the most cash. Done carefully, it works for both sides. Done on a handshake, it rarely does.
Questions people ask
What does it mean when someone finances the sale of their business?
Seller financing means the business owner acts as the bank. You pay a down payment upfront, typically ten to thirty percent, then sign a promissory note to pay the rest back in installments with interest over a set number of years, usually three to seven. The seller keeps a legal claim to the business assets until you finish paying.
Why do Hmong-owned businesses use seller financing so often?
Many Hmong-owned restaurants, markets, salons, and shops are cash businesses with family labor and informal bookkeeping that banks won't easily lend against. Banks want to see documented collateral they can repossess. Seller financing works because the actual owner knows the business's real value and is willing to extend credit based on that knowledge and existing trust.
What should I absolutely check before agreeing to buy a business this way?
Get three years of actual tax returns, not just the seller's profit and loss statement. Reconcile reported revenue against bank deposits. Search for existing liens on the business assets. Ask about unpaid sales tax and successor liability. Confirm the lease can transfer to you and all licenses renew. Walk through the physical space and ask the seller directly, more than once, why they're selling.
What happens if I can't make a payment on the seller's note?
That depends on what the promissory note says. The contract should spell out how many days you have to catch up before the seller can declare the entire remaining balance due or repossess the business assets. This is why getting every term in writing reviewed by an attorney working for you, not the seller's attorney, is critical.
Written by
Hmong Network Team
Directory & Digital Services
We run the Hmong Network directory and do the web design and SEO/AEO work behind the results in our case studies. These guides come out of that same hands-on work with Hmong-owned businesses — not secondhand research.
