
LLC or Sole Proprietorship? How to Actually Decide
TL;DR
A sole proprietorship costs nothing and starts the moment you make your first sale, but it leaves your house, car, and savings exposed if the business gets sued. An LLC costs money and paperwork upfront in exchange for a real wall around your personal assets — the right choice depends on what you're actually risking, not which one sounds more official.
What Each Structure Actually Protects You From
A sole proprietorship isn't something you apply for. It's what you already are, automatically, the moment you start selling goods or services under your own name or a DBA. No state filing, no separate tax return, no extra fees — you just start working and report the income on your own Form 1040. That simplicity is exactly why so many first businesses, from a weekend catering table to a home-based sewing or paj ntaub business, start this way without anyone ever sitting down to decide it. If you haven't mapped out everything else a new business needs, the full startup checklist covers what actually has to happen before you take your first customer dollar.
The tradeoff is that there's no legal separation between you and the business. If a customer slips in your shop, a client claims your work cost them money, or a supplier sues over an unpaid invoice, they're not just suing "the business" — they're suing you, personally. Your house, your car, your savings account, even a spouse's shared assets in some states, can be reached to satisfy a judgment. An LLC (limited liability company) exists specifically to draw a line there. Once it's properly formed and run like a real, separate entity, a lawsuit against the business generally stops at the business's own assets and can't reach your personal ones. That word "properly" is doing a lot of work, and it's worth its own section further down — an LLC that exists only on paper while you run everything through your personal checking account offers a lot less protection than most owners assume.
The Question That Actually Decides This: What's at Risk If Something Goes Wrong
Forget which structure sounds more professional on a business card — that's not the decision that matters. The real question is: what happens if this goes wrong?
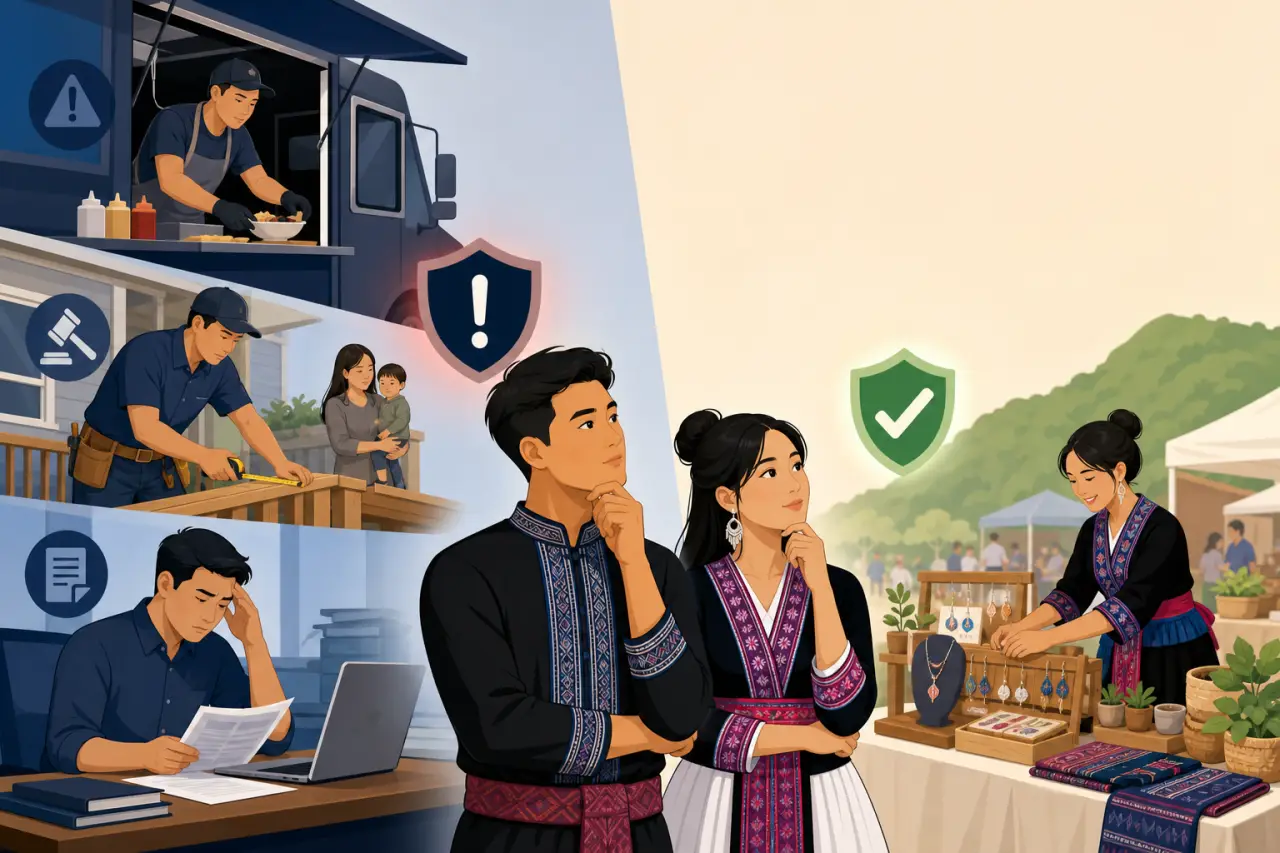
- A restaurant or food truck carries foodborne-illness risk every single day it's open.
- A contractor, landscaper, or in-home childcare provider is working on or around other people's property and other people's kids.
- A bookkeeper, insurance agent, or web designer can be sued over advice that cost a client money, sometimes years after the work was done.
Each of those is a real exposure that a sole proprietorship does nothing to contain.
Compare that to someone selling handmade jewelry or textiles at weekend markets a few times a year, with a few thousand dollars of income and almost no physical risk to a customer. The liability exposure there is genuinely low, and paying a state filing fee plus ongoing compliance costs to guard against a risk that's unlikely to materialize can be money better spent elsewhere in the business. Match the structure to what you're actually risking, not to what a friend or relative did for their business — their risk profile might look nothing like yours.
What It Actually Costs to Set Up — and Keep Running
A sole proprietorship costs nothing to start. If you operate under anything other than your own legal name, most states or counties require you to file a "doing business as" (DBA) or fictitious name registration, which usually runs somewhere between twenty and a hundred dollars, sometimes with a small publication requirement depending on where you live. Beyond that, there's no state fee, no annual report, and no separate legal entity to maintain.
An LLC has real costs on both ends:
- The initial state filing fee typically runs anywhere from under fifty dollars to a few hundred, depending on the state.
- Most states also charge an ongoing fee — an annual report, a franchise tax, or both — to keep the LLC in good standing, which can range from nothing at all to several hundred dollars a year.
- Some owners also pay a registered agent service, usually under two hundred dollars a year, if they don't want their home address listed as the public point of contact for legal notices.
None of this is a reason to avoid an LLC if you genuinely need the liability protection, but it's real money and real paperwork you have to keep up with every year, not a one-time fee you pay once and forget. It's also worth building the LLC's own credit history separately from your personal credit from day one — if you're coming off a rough stretch, rebuilding your business credit is often easier to do under a fresh, separate entity than it is to fix personal credit alone.
How Each One Is Taxed — and Where People Get It Wrong
Here's the part that surprises a lot of new owners: for tax purposes, a single-member LLC and a sole proprietorship are treated almost identically by default. The IRS calls a one-owner LLC a "disregarded entity," meaning you still report the business's income and expenses on a Schedule C attached to your personal return, and you still owe self-employment tax on the profit, the same as a sole proprietor does. Forming an LLC does not, by itself, lower your tax bill.
Where taxes can actually change is if you later elect to have the LLC taxed as an S-corporation, which lets an owner split income between a salary and a distribution — see how to pay yourself for how owners actually decide that split — and can reduce the self-employment tax owed on the distribution portion. That election comes with its own costs, though, like running actual payroll and filing a separate business tax return, and it usually only makes sense once the business is consistently profitable enough to justify the extra accounting. Don't form an LLC expecting a tax break on day one; form it for the liability protection, and treat any tax election as a separate decision to revisit once there's real, steady profit to plan around.
Why So Many Family Businesses Start as Sole Proprietorships — and Where That Quietly Stops Working
A lot of Hmong-owned businesses start exactly the way sole proprietorships are built for: a side hustle that turns into a full storefront, a family recipe that becomes a restaurant, a skill someone already had that turns into a salon or a construction crew. Nobody sits down on day one and incorporates — you just start selling, and the sole proprietorship happens by default while you figure out whether the idea even works.
That's a completely reasonable way to start. But there are specific moments where the risk changes enough that it's worth stopping to reconsider — moments that all raise the stakes of what a lawsuit or a bad debt could actually cost you:
- Signing a commercial lease
- Taking out a business loan or equipment financing
- Hiring your first employee
- Buying a food truck or work van
- Bringing on a business partner
None of those moments legally require an LLC, but each one is a natural checkpoint to ask the "what's at risk" question again, because the honest answer has usually changed since you first started.
Setting Up the LLC So It Actually Protects You
Filing the paperwork to form an LLC is the easy part. The protection only holds up if you actually run the business like a separate entity afterward, and this is where a lot of owners quietly undo their own liability shield without realizing it:
- Open a business bank account, and never pay personal expenses out of it or deposit business income straight into your personal account.
- Get a free EIN from the IRS and use it instead of your Social Security number on business accounts and contracts.
- Write an operating agreement, even for a single-member LLC where it's not always legally required, so there's a clear paper trail showing the business operates under its own rules.
A court deciding whether to let a plaintiff go after your personal assets despite the LLC is looking for exactly this kind of evidence — did you treat the business as genuinely separate, or was the LLC just a name on a bank account you never actually used that way? This is usually called "piercing the corporate veil," and it happens most often to owners who filed the LLC paperwork once and then kept running the business exactly the way they did as a sole proprietor. And one more thing an LLC doesn't do: it doesn't replace insurance. General liability coverage, and workers' comp the moment you hire anyone, are what actually pay out on a claim; the LLC just decides whether a claim beyond what insurance covers can reach your house.
What Changes When a Spouse, Sibling, or Adult Child Joins the Business
The moment a spouse, sibling, or grown child is genuinely a co-owner and not just an employee, the sole proprietorship option is off the table entirely — a sole proprietorship can only have one owner. Two or more owners running a business informally, with no paperwork, are legally a general partnership by default, which offers even less protection than a sole proprietorship: each partner can be held personally responsible for decisions the other partner made, even ones they didn't know about or agree with.
A multi-member LLC replaces a lot of assumptions that families tend to leave unspoken because talking about them out loud feels awkward or distrustful, with an operating agreement that spells out:
- Who owns what percentage
- Who has authority to sign contracts or spend money above a certain amount
- What happens if one owner wants out, dies, or gets divorced
It isn't about distrust — it's the same reason you'd want directions written down before a road trip instead of assuming everyone agrees on where you're going. Family businesses that skip this step often find out how differently everyone remembered "the agreement" only after a disagreement, a divorce, or a death forces the question, which is a much harder time to work it out than right now.
Converting From a Sole Proprietorship to an LLC Later Doesn't Mean Starting Over
If you started as a sole proprietorship and the business has grown into something with real risk attached, converting to an LLC later is a normal, common move — not a sign you got it wrong the first time. The core steps are the same regardless of what state you're in:
- File the LLC formation paperwork with your state.
- Get a new EIN specifically for the LLC (you can't keep using your old sole-proprietor EIN, since the IRS treats the LLC as a new taxpayer even if the ownership hasn't changed).
- Open a new business bank account under the LLC's name.
From there, the less glamorous but equally important work is updating everything that still points to you personally:
- Business licenses and permits
- Your lease, if you have one
- Contracts with vendors and clients
- Your business insurance policy
- Any accounts with payment processors or delivery platforms
None of that has to happen in a single day, but until it's done, some of those relationships are still technically with you as an individual rather than with the LLC, which quietly limits how much protection you're actually getting. Keep your old sole-proprietorship records for tax purposes even after the switch — you'll still need them for that year's filing — but treat the conversion date as a clean line between what the old structure covered and what the new one does. Either way, matching the structure to where the business actually is right now — not where it started — is what building a business that lasts actually looks like in practice.
Written by
Hmong Network Team
Directory & Digital Services
We run the Hmong Network directory and do the web design and SEO/AEO work behind the results in our case studies. These guides come out of that same hands-on work with Hmong-owned businesses — not secondhand research.
