
The Small Business Startup Checklist That Actually Matters
TL;DR
Most startup checklists are 40 items long and half of them don't matter yet. Here's the short version — the handful of things that genuinely need to happen before you take your first dollar from a customer, and what can safely wait until month three.
Talk to Ten People Before You Design a Logo
Skip the generic checklists that have you designing a logo before you know if anyone wants what you're selling. The first real step is validating demand — talk to ten potential customers, not your family, about the actual problem you're solving and whether they'd pay for your solution. If you can't get a stranger to say "yes, I'd buy that," fix the idea before you fix the paperwork. That's really the honest version of starting up — proof before paperwork, not the reverse.
The test that actually works is asking for money, not opinions. "Would you use this" gets a polite yes almost every time — people don't want to discourage you. "Would you put down a $20 deposit for a spot in my first batch" gets you the truth in about thirty seconds. If you're planning a food business, cook for a small paid event before you lease a kitchen. If it's a service — hair, lashes, tax prep, translation help — take three paying clients at your planned price before you print business cards. The goal isn't a full pilot program, it's proof that real money will change hands for what you're building.
This step also tells you who your actual first customers are, which matters more than it sounds. A lot of new business owners assume their first customers will come from the broader community, and instead their first ten sales come from a specific, narrower group — people who work near a certain location, people who found them through a specific Facebook group, people solving a specific version of the problem. Knowing that early changes where you spend your first marketing dollar.
Pick a Structure, Get an EIN, Open a Real Business Account
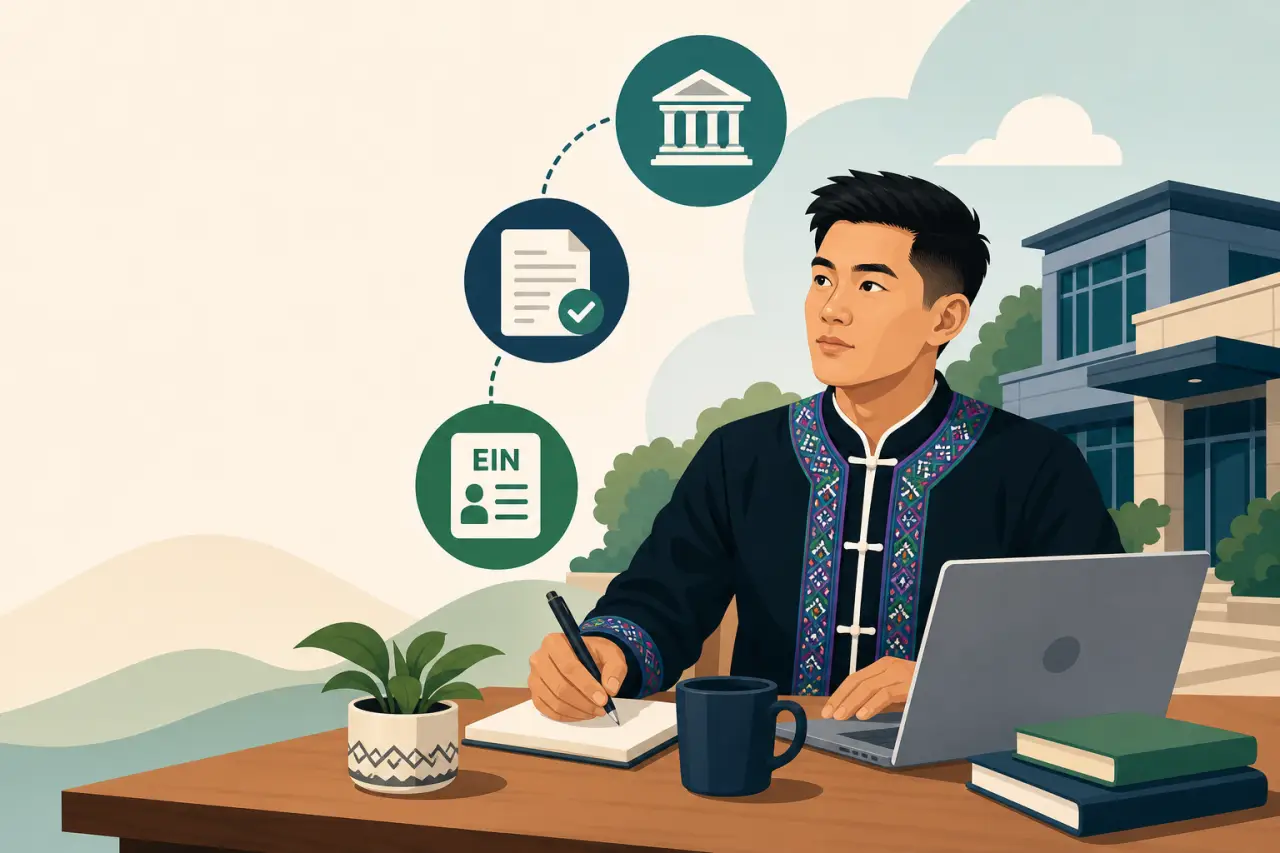
Once demand is real, lock in the boring-but-essential legal basics: pick a business structure, register your business name, and get an EIN from the IRS — it's free and takes ten minutes online at irs.gov. Most small businesses starting out choose between two structures:
- Sole proprietorship — simplest, but your personal assets aren't protected if something goes wrong
- LLC — a small amount of paperwork and a state filing fee, but it separates the business's liabilities from your house and your savings
If your business involves physical risk to customers — food, personal care services, anything with equipment or a physical location — the LLC's liability protection is worth the extra step, not a nice-to-have. If you're still weighing the two, choosing an LLC or sole proprietorship usually comes down to exactly this — how much physical or financial risk the business carries in its first year.
Open a dedicated business bank account immediately, even if you're a sole proprietor with no legal requirement to. Get a debit card tied to it and, once you qualify, a business credit card you pay off in full. Mixing personal and business money is the single most common thing that turns a good year into a tax-season nightmare — it also undermines the liability protection an LLC is supposed to give you, because commingled funds are exactly what makes a court willing to treat the business and the owner as the same thing in a lawsuit. Every dollar the business earns goes into that account first, even if you're going to pay yourself out of it the same day.
The Four Things Almost Everyone Skips Until It Costs Them
Insurance, permits, agreements with family, and agreements with vendors are the four things almost everyone skips until they cost something:
- Insurance gets skipped constantly because it feels optional until the moment it isn't — general liability coverage is inexpensive relative to what one accident, one bad batch of food, or one lawsuit can cost you. If you'll have even one employee, workers' compensation isn't optional in most states, and if you're selling anything people consume or use on their body — food, skincare, supplements — product liability coverage is the policy that actually matters most.
- Local permits and licenses are just as commonly skipped. Requirements vary wildly by city and industry, so a five-minute call to your city clerk's office can save you a shutdown later. This hits home-based businesses especially hard: cottage food laws let you sell certain foods made in a home kitchen in many states, but the list of what qualifies is specific, and cosmetology and personal care services almost always require a state board license and inspected space, even for work done from a converted garage or spare room.
- If you're bringing on family or close friends to help — which happens constantly in the earliest months of a new business — put the basic terms in writing anyway: pay rate, hours, and what happens if it doesn't work out. It feels unnecessary between people who trust each other, right up until an unpaid family member expects a share of the business a year later and there's nothing on paper defining what they were actually promised.
- If you're working with any outside vendor — a supplier, a contractor doing your buildout, a co-packer — get the agreement in writing before money or product changes hands, even if it's a one-page document. A verbal agreement with someone you've known for years is still nearly impossible to enforce if the relationship sours.
Where Your Money Actually Needs to Go Every Week
Set aside money for taxes from day one — putting a simple 25 to 30 percent of every payment into a separate savings account keeps a self-employment tax bill from becoming a surprise. If you expect to owe more than $1,000 for the year, the IRS expects quarterly estimated payments, not one lump sum in April — missing those quarters can add penalties on top of a bill you already weren't ready for.
Price your product or service to cover your real costs, not what feels comfortable to charge people you know. This is one of the fastest ways a new business quietly fails: underpricing out of obligation to family, church members, or people from your own community, because charging full price to someone you'll see at the next gathering feels awkward. Do the math once, using three numbers:
- Cost of goods or materials
- Your actual time, at an hourly rate you'd accept from anyone else
- A margin on top
Then hold that price for everyone. You can offer an occasional discount as a deliberate choice; you can't run a business on discounts you never chose to give.
Build a cash buffer before you need one, even a small one. A slow month, a broken piece of equipment, or a late-paying client shouldn't be able to shut you down in your first year. Even $500 to $1,000 set aside before you need it is the difference between a bad week and a business-ending one.
Get Found Before You Need to Be Found
Get listed somewhere customers can actually find you before you need customers, not after — a directory listing or simple website takes a day to set up and starts working for you immediately, even while you're still finalizing your permits and your first batch of inventory. Claim your Google Business Profile the same day you settle on a business name; it's free, and it's often the very first thing a potential customer sees when they search for what you do. For a step-by-step walkthrough, taking your business online covers the full sequence, from claiming your listing to your first real website.
Word of mouth inside a tight community is genuinely powerful and it's usually how the first real customers show up — but it's not a distribution strategy on its own, because it caps out at the size of the network that already knows you. Pair it with something that reaches beyond people who already know your family:
- A directory listing
- A basic website with your hours and a way to contact you
- A couple of clear photos of your actual product or workspace
The businesses that grow past their first year are almost always the ones that got real strangers finding them online within the first few months, not just referrals from people already close to the owner.
Ask your first happy customers for a review the same week they buy from you, while the experience is still fresh — don't wait until you have a hundred customers to start collecting the first ten reviews. A handful of specific, genuine reviews early on does more for a new business's credibility than a large number of vague ones later.
 Claim your free business listingFree forever — no credit card required.
Set Up Bookkeeping Before You Have Anything to Book
Set up simple bookkeeping habits from the very first sale:
- Track income and expenses, even if it's just a simple spreadsheet or a free tool built for small businesses
- Save every receipt — a folder on your phone works fine — and note what it was for the moment you get it, not three months later when you can't remember
- If you drive for the business, track your mileage from day one; it's one of the easiest deductions to lose entirely just because nobody wrote it down as it happened
This matters for two reasons beyond taxes. First, you can't price anything correctly or know if you're actually profitable without knowing your real numbers — plenty of small businesses feel busy and still lose money every month because nobody is looking at the full picture. Second, the day you want a business loan, a storefront lease, or a wholesale account with a supplier, the first thing they'll ask for is financial records. A business with a year of clean, simple records looks far more credible to a lender than one with a shoebox of receipts, even if the actual revenue is the same.
Who's Actually on Your Team, and Who Just Thinks They Are
Family involvement is one of the biggest advantages a new business can have, and one of the biggest sources of confusion if roles aren't defined early. Decide, in plain terms, which of three different relationships each person in the business actually has:
- Who is actually working in the business
- Who is an investor
- Who is just enthusiastic and offering opinions
Treating them as interchangeable is how disagreements over money and decision-making show up later, often after the business is already succeeding and there's something worth arguing over.
Find at least one advisor outside your own circle who has actually run a business before — a mentor through your local SBA office or SCORE chapter, another established business owner in your community, or a small business development center at a nearby college. These are free in most cities. The value isn't generic encouragement; it's someone who can tell you, specifically, whether your lease terms are reasonable, whether your pricing makes sense for your market, or whether the contract someone handed you is normal or a problem. Family and friends are often the first people you tell about the business — they're rarely the right people to ask when the questions get technical.
What Can Wait Until Month Three
Just as important as knowing what to do first is knowing what genuinely doesn't need to happen yet. None of these make the first sale happen, and all of them are easier to get right once you know more about your actual customers than you do on day one:
- A polished logo
- A custom website with every feature
- Business cards
- Branded packaging
- A second location
- A full hiring plan
The same goes for expensive equipment and large inventory orders. Buy or lease the minimum that lets you serve real customers now, and reinvest as sales prove the business out, rather than borrowing against a guess about how fast you'll grow. A loyalty program, a subscription offering, or a second product line are all good ideas worth building — just not before the first, simplest version of the business is reliably making money on its own. The businesses that stall in year one are rarely the ones that started too simple; they're almost always the ones that tried to do everything at once before anything was actually working. If you're weighing where to spend your limited time and money first, what new owners should focus on first is worth reading before you decide.
Questions people ask
What should I do before I design a logo for my business?
Talk to ten potential customers first—not your family—about whether they'd actually pay for what you're selling. The real test is asking for money, not opinions. Cook a paid event before leasing a kitchen. Take three paying clients at your planned price before printing cards. Proof that real money will change hands matters more than a polished brand.
Should I start as a sole proprietor or an LLC?
If your business involves physical risk to customers—food, personal care, equipment, or a physical location—choose an LLC. The liability protection is worth the extra paperwork and state filing fee. For lower-risk businesses, a sole proprietorship is simpler. Either way, open a dedicated business bank account immediately to keep personal and business money separate.
What four things do most new business owners forget until they cause problems?
Insurance, local permits, written agreements with family helpers, and written vendor contracts. General liability coverage is inexpensive compared to what one accident costs. Permit requirements vary by city and industry—call your city clerk. Put pay rates and terms in writing even with family. Get vendor agreements on paper before money or product changes hands.
How much money should I set aside for taxes?
Put 25 to 30 percent of every payment into a separate savings account. If you'll owe more than $1,000 for the year, the IRS expects quarterly estimated payments, not one lump sum in April. Missing quarterly payments adds penalties on top of your bill. Start setting money aside from your first sale.
Written by
Hmong Network Team
Directory & Digital Services
We run the Hmong Network directory and do the web design and SEO/AEO work behind the results in our case studies. These guides come out of that same hands-on work with Hmong-owned businesses — not secondhand research.
